
Behind on Your Mortgage in Utah? Your Options
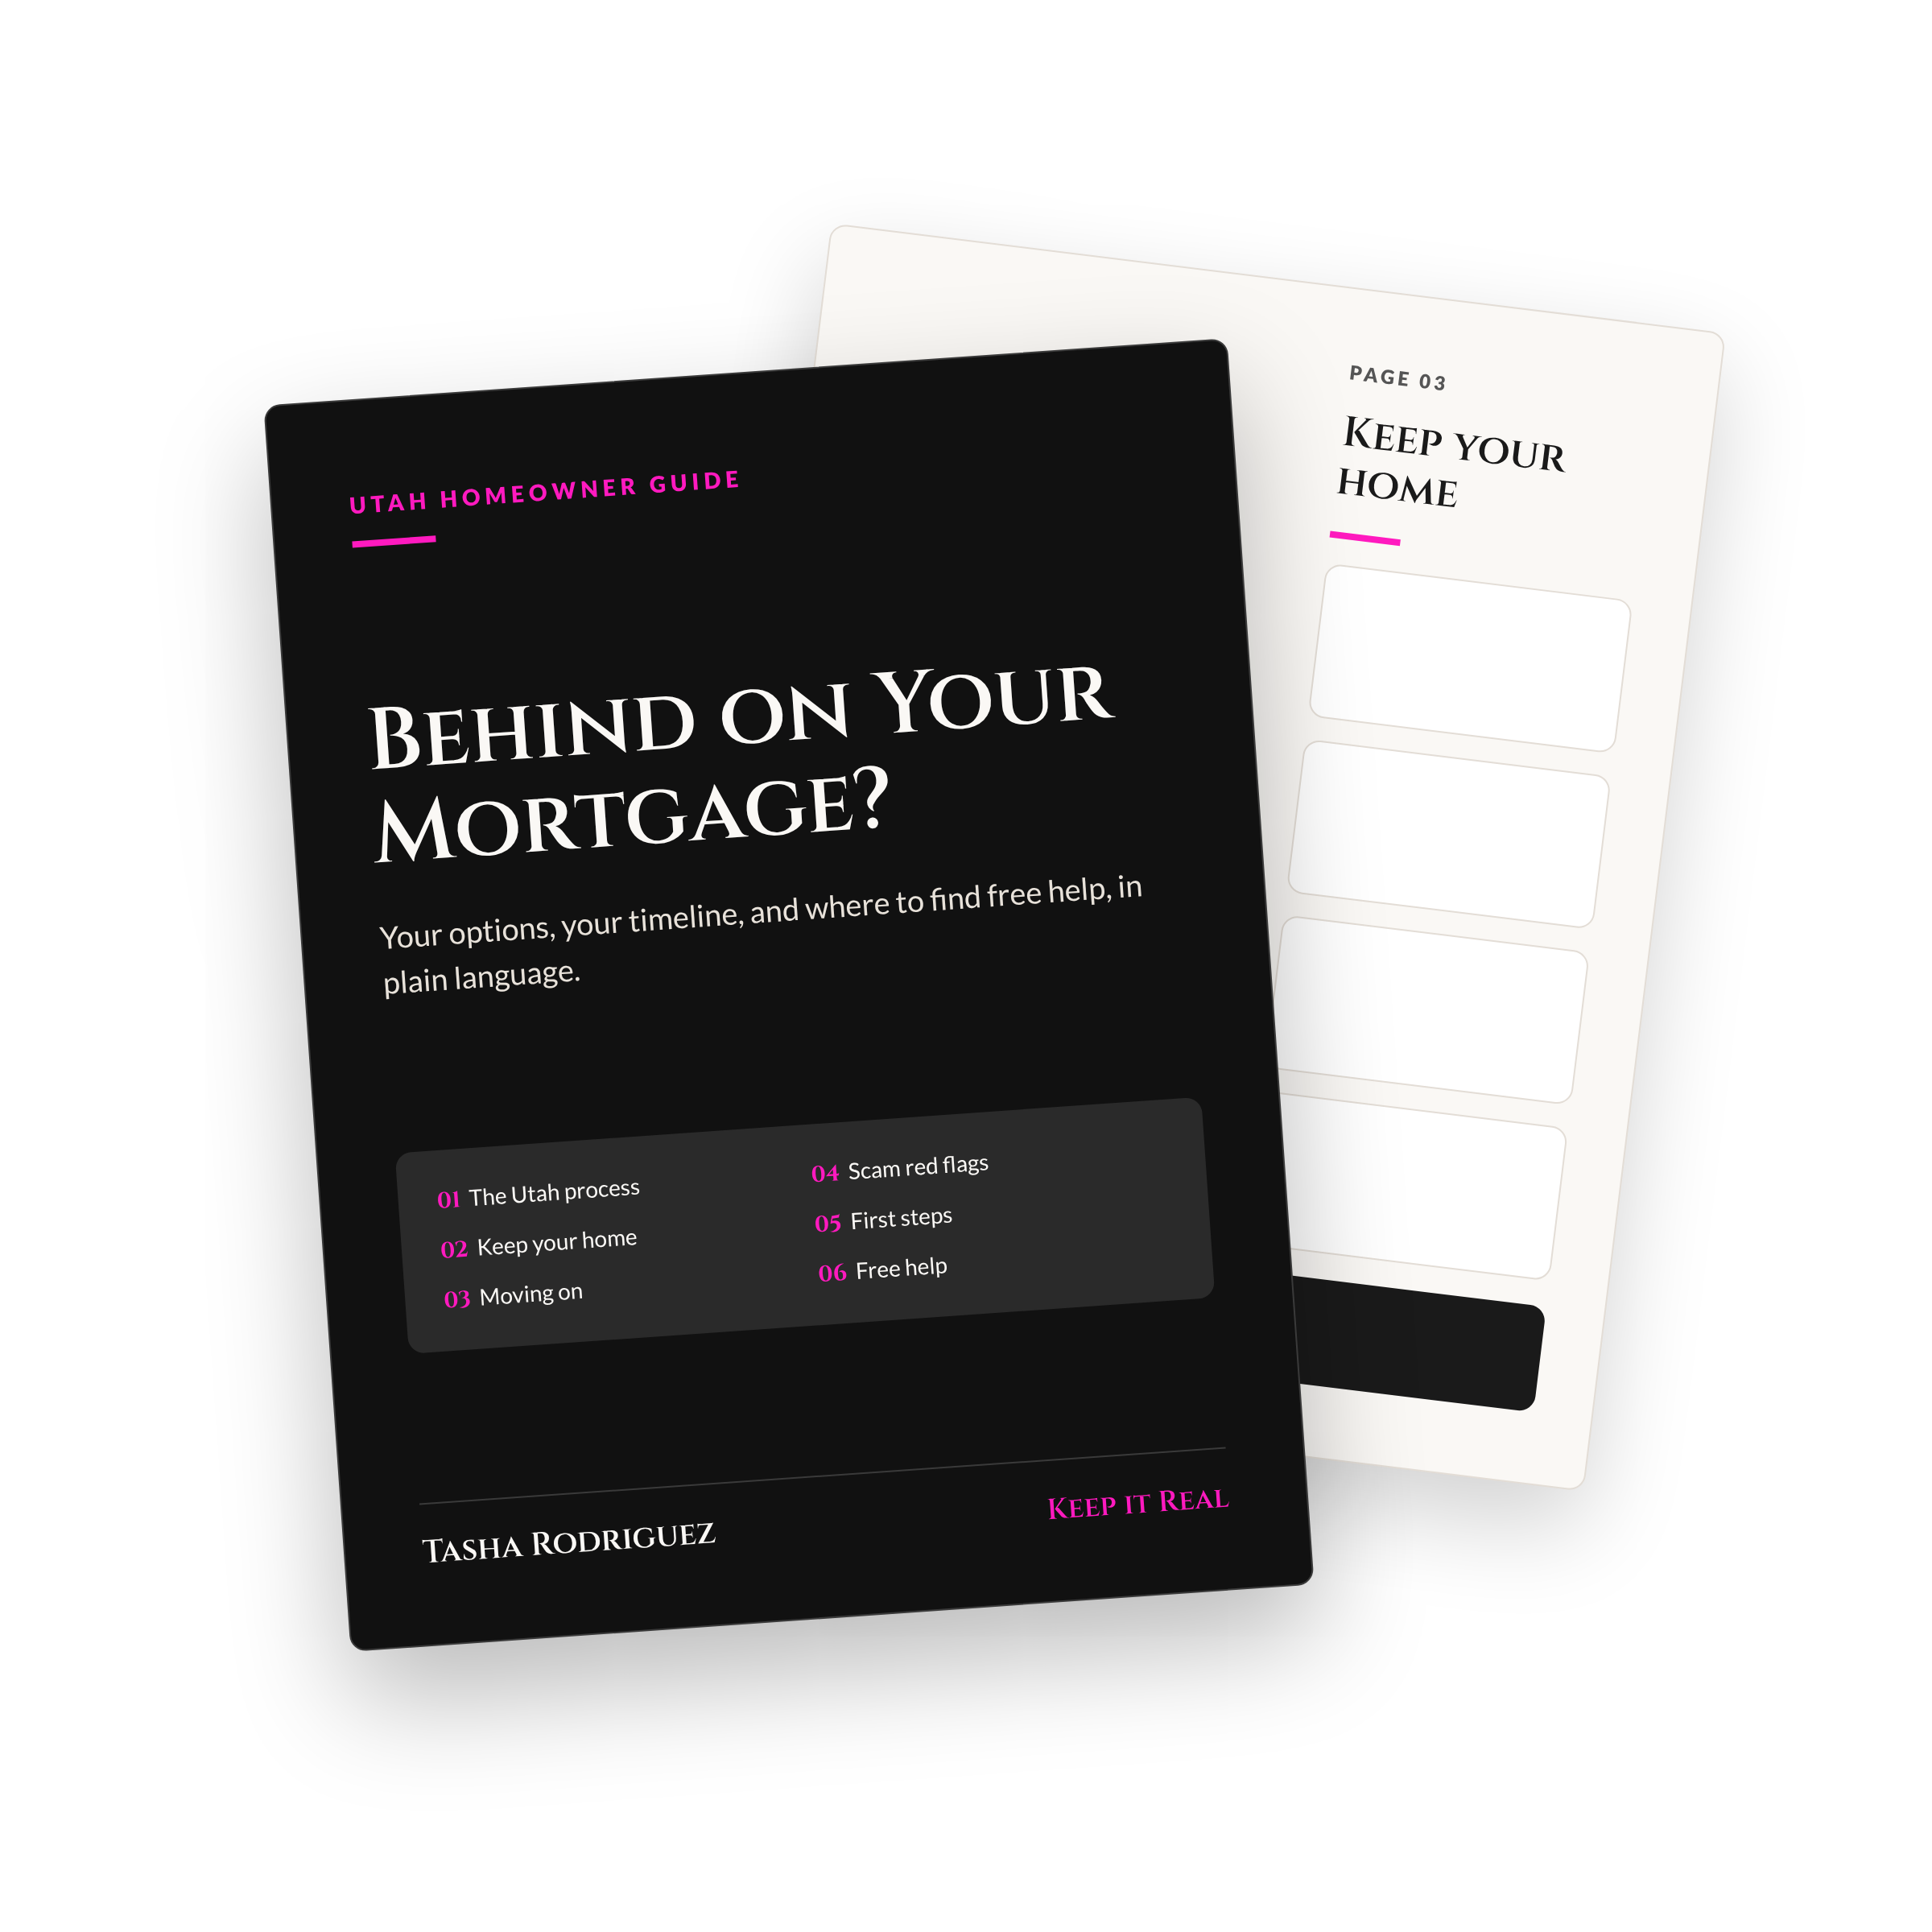
What's Inside the Guide
How the Utah process works, step by step, including your 3-month window after a Notice of Default
Six ways to keep your home, from reinstatement to a loan modification
Your options if you decide to move on: a traditional sale, a cash offer, a short sale, or a deed in lieu
Scam red flags to watch for
A first-steps checklist you can finish this week
Free help: HUD-approved counselors, Utah 211, and legal aid
Who This Guide Is For
Utah homeowners who have missed a payment or two and want to get ahead of it
Anyone who just received a Notice of Default and isn't sure what it means
Homeowners deciding between keeping the home and selling
Family members helping a parent or relative who has fallen behind
Utah Mortgage and Foreclosure Questions
Straight answers to what Utah homeowners ask me most.
This guide is general information, not legal advice. Every situation is different, so talk with a Utah real estate attorney or a HUD-approved counselor about yours.
How long does foreclosure take in Utah?
Most Utah foreclosures are nonjudicial. After the Notice of Default is recorded, the trustee must wait at least 3 months before giving a Notice of Sale, and the sale must be noticed at least 20 days ahead, so the shortest path from Notice of Default to auction is about 4 months. Federal rules generally keep a servicer from starting foreclosure until a borrower is more than 120 days behind.